
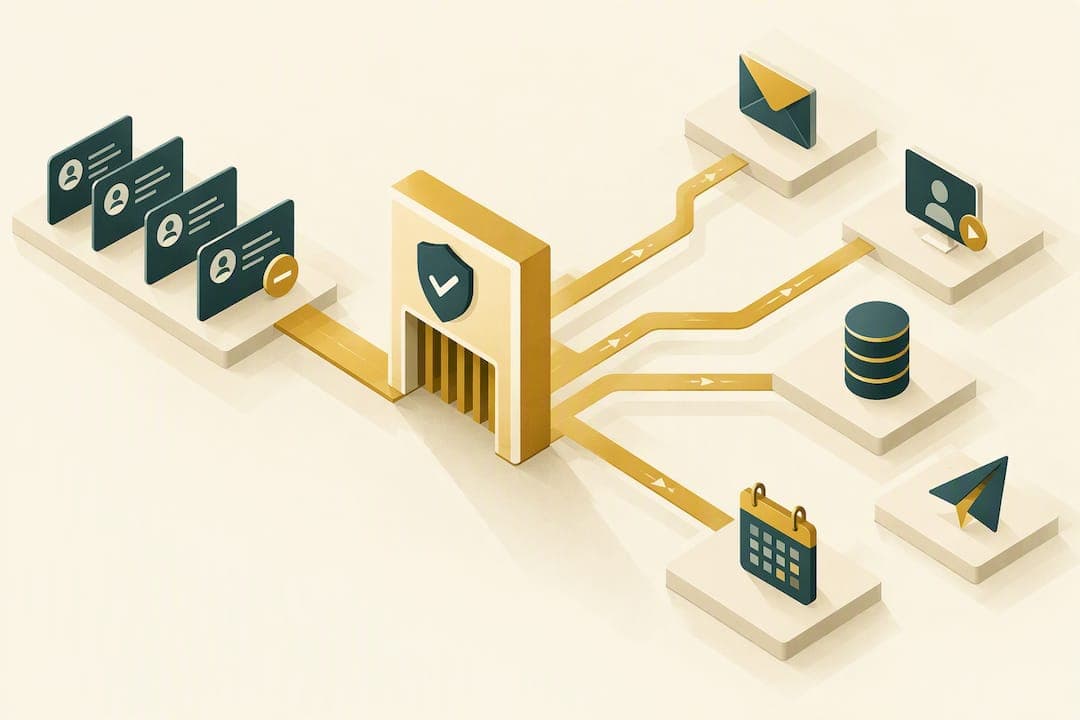
Unsubscribe management for financial advisors means maintaining a centralized, auditable suppression status that stops marketing across every vendor and channel, not just the email platform that sent the last campaign. The single measurable outcome a compliant firm must hit is simple to state and hard to prove: when a prospect opts out, that status has to be honored everywhere, within the timeline regulators expect, with a record showing it happened.
TL;DR:
- A single, centralized suppression flag must be maintained and synchronized across all systems and channels, including CRM, email platforms, and event registration tools.
- Vendors must retain proof of suppression actions, such as timestamps and method details, and vendor contracts should specify processing times and prohibitions on transferring suppressed contacts.
- An end-to-end testing process, including simulated opt-outs across all channels, is necessary to prove the system's compliance and prevent channel drift.
- Regulatory frameworks from the FTC, SEC, and FINRA impose strict requirements for honoring opt-outs within specified timelines and supervising all digital communication channels.
- Most advisors benefit from using integrated marketing systems that share contact records and suppression statuses, reducing manual gaps and regulatory risks.
Table of Contents
- What unsubscribe management means for an RIA
- Core regulatory requirements that shape unsubscribe systems
- Operational checklist for a compliant unsubscribe system
- Technical architecture that makes suppression provable
- Implementation tests and what examiners expect to see
- What a working advisor marketing system actually looks like in practice
- How Mastermind Advisor Marketing handles this for you
- FAQ
- Sources
What unsubscribe management means for an RIA
For an independent advisory practice, unsubscribe handling touches more than a newsletter list. It covers webinar and seminar invitations, CRM-triggered drip sequences, outsourced email senders, and any event registration platform that collects a prospect's contact information. A suppression request made through one channel has to carry through all of them, or the firm is technically still marketing to someone who opted out.
The regulatory exposure comes from three directions at once. The FTC's CAN-SPAM compliance guide requires a working opt-out mechanism and sets a hard clock on honoring requests. The SEC's marketing rule ties advertising communications to recordkeeping obligations that advisers must meet directly. FINRA guidance adds supervision expectations across whatever digital channels a firm actually uses, not just the ones it planned for.
Beyond the regulatory angle, sloppy unsubscribe handling creates its own business risk:
- A prospect who keeps getting emails after opting out often files a complaint instead of just ignoring the next message.
- Lost goodwill with a referral source or center of influence can cost more than the lead was worth.
- Examiners frequently use unsubscribe and suppression failures as a signal to dig deeper into a firm's broader marketing supervision.
Core regulatory requirements that shape unsubscribe systems
Three regulatory frameworks define how an advisor's unsubscribe system has to function, and each one pulls in a slightly different direction.
- FTC CAN-SPAM requires a clear, conspicuous opt-out mechanism that can process requests for at least 30 days and must be honored within 10 business days, according to the FTC's compliance guide. The sender cannot charge a fee, demand more than an email address, or require more than a single reply or one web page to complete the request.
- SEC marketing rule and books-and-records obligations treat adviser marketing communications as advertisements subject to retention requirements. The SEC's investment adviser marketing guidance points to Rule 204-2, which obligates advisers to keep the sent version of a communication along with supporting records, and examiners focus specifically on these advertising files during reviews.
- FINRA communications supervision extends the obligation across every digital channel a firm actually uses. FINRA's guidance on communications with the public calls out texting, social media, collaboration apps, and electronic sales seminars as channels firms must supervise, meaning a suppression flag that only lives inside the email tool leaves gaps a regulator can find.
None of these three frameworks talks about unsubscribe handling the same way, but they converge on one practical demand: the firm has to be able to show, after the fact, that an opt-out request was captured and respected everywhere it mattered.
Operational checklist for a compliant unsubscribe system
Building or auditing an unsubscribe process comes down to five concrete actions.
- Implement a global suppression flag in the firm's canonical data source, whether that is the CRM or a dedicated compliance record, and require every vendor contract to honor that flag rather than maintaining its own isolated list.
- Capture evidence for every opt-out event, including the timestamp, the channel it came through, the send or campaign ID, the audience segment, and the vendor that executed the original send.
- Design a preference center with category choices alongside a clearly labeled option to stop all marketing messages, and keep transactional or relationship communications in a separate classification so marketing unsubscribe never accidentally silences account notices.
- Write suppression clauses into vendor contracts covering how fast a vendor must process a suppression event, a prohibition on transferring suppressed contacts to other lists, and a requirement to retain evidence of the action taken.
- Extend controls across every channel in use, including webinar and seminar platforms, CRM automation sequences, texting tools, and any marketing activity happening from a representative's personal device.
Pro Tip: Treat every outsourced sender, including webinar platforms and seminar registration tools, as a channel that needs its own documented suppression check, not an extension of the email list.
Firms that skip the contractual piece often discover the gap only when an examiner asks a vendor directly whether suppressed contacts can still receive event invitations. An SEC marketing-rule compliance checklist is a useful reference point when drafting these vendor terms, since the retention obligations described there extend to any third party executing sends on the firm's behalf.
Technical architecture that makes suppression provable
The technical design question is whether suppression status actually propagates, in both directions, between every system that touches a contact.
- A canonical suppression flag should live in one system of record, with real-time or near-real-time two-way sync to the CRM, the email platform, and any webinar or seminar registration tool, rather than a nightly batch job that leaves a gap window.
- Each send and each opt-out event needs stored metadata: a send ID, a segment ID, the timestamp of the user's action, a vendor identifier, and a reference to the approval record for that piece of content.
- Deduplication matters more than it looks. Role-based addresses, aliases, and duplicate contact records across CRM and email systems can all let a suppressed person keep receiving mail under a slightly different entry.
- Every vendor relationship needs a documented fallback plan for processing outages, including a corrective timeline for catching up once the outage clears, since a vendor failure does not pause the firm's regulatory clock.
The financial advisor email campaign setup guide covers the practical side of configuring these integrations, which is useful once the policy decisions above are settled and someone has to actually wire the systems together.
Implementation tests and what examiners expect to see
Proving a system works means testing it the way an examiner would.
- Run a full end-to-end opt-out simulation across every channel in use, email, webinar platform, CRM automation, and texting, and record the outcome and timestamp for each.
- Assemble an audit sample that includes sent message copies, the segment or audience export tied to each send, suppression transaction logs, vendor confirmation records, and the approval history for the content itself.
- Set a reconciliation cadence, comparing the canonical suppression list against every vendor's own list on a fixed schedule and flagging exceptions immediately rather than at renewal time.
- Keep the documentation examiners actually ask for: written policies, training logs showing staff understand them, retained copies of sent messages, and the suppression transaction records tying it all together.
FINRA's exam guidance has repeatedly flagged channel drift, where a contact is suppressed in one tool but a different platform keeps sending, as a recurring supervisory gap found during reviews of firm communications. A quarterly end-to-end test with compliance sign-off, retained as its own file, closes that gap before an examiner finds it first.
What a working advisor marketing system actually looks like in practice

Most of the unsubscribe problems advisors run into trace back to marketing built for generic small businesses, then retrofitted for a regulated industry. Some marketing services build webinars, seminars, and content marketing designed from the start for the compliance realities and long buying cycles unique to financial advisory practices, with custom CRM integration and automated email follow-ups built in rather than bolted on.
That integration is what makes suppression status provable instead of theoretical, because the CRM, the email automation, and the event systems share the same contact record from day one. The independent advisor compliance marketing checklist and the why email marketing converts advisors guide both walk through how that structure holds up under scrutiny without sacrificing the engagement that makes the marketing worth running.
— Josh
How Mastermind Advisor Marketing handles this for you
Every piece of the checklist above, suppression flags, vendor contract terms, evidence capture, cross-channel supervision, is often included in some turnkey marketing systems rather than being something your firm has to engineer from scratch.
- Webinars and seminars built with registration and follow-up tracked inside one connected system, not three disconnected vendors.
- Custom CRM integration that keeps suppression status synchronized across every touchpoint instead of living in a spreadsheet.
- A compliance-friendly content library so campaigns are built on material already structured for retention and review.
- Automated email follow-ups that respect suppression status the moment it changes.
If your current marketing setup cannot answer, with evidence, whether a suppressed contact is truly suppressed everywhere, visit the Mastermind Advisor Marketing services page to see how a turnkey, advisor-specific system replaces that guesswork with a documented process.
FAQ
How many days does a business have to honor an email opt-out?
The FTC requires opt-out requests to be honored within 10 business days, and the opt-out mechanism itself must be able to process requests for at least 30 days after a message is sent, according to the FTC's CAN-SPAM guide. A compliant system should aim to process requests faster than the deadline, not right up against it.
Does a subscription or membership status remove CAN-SPAM obligations?
No. The FTC has clarified that subscription or membership relationships do not remove a recipient's right to opt out when a message's primary purpose is commercial. Advisors should classify borderline messages with compliance counsel rather than assuming an existing relationship covers continued marketing.
What records must an adviser keep for marketing emails?
Under the SEC's marketing rule framework, advisers must keep the sent version of each advertisement along with supporting records such as the audience segment, approval history, and any suppression events tied to it, as described in the SEC's adviser marketing guidance. Examiners typically request these records together, not as separate files.
Does a preference center need a 'stop all marketing' option?
Yes. A preference center can let recipients choose categories of messages, but it still needs a clearly labeled option to stop all marketing messages, since relying only on category opt-outs can leave a firm unable to prove full suppression occurred.
What does FINRA expect for supervising marketing across channels?
FINRA guidance calls for firms to define permitted digital channels, supervise them actively, and watch for channel drift, where suppression in one tool does not carry over to another platform like texting or social media, per FINRA's communications guidance. A single, centralized suppression flag shared across every channel is the most direct way to close that gap.
Sources
- CAN-SPAM Act: A Compliance Guide for Business | Federal Trade Commission
- Investment adviser marketing | SEC
- Communications with the public | FINRA